Hallo! Tracked shipping to Austria with Delivery Duty Paid for just €3.99  

Ship to
Austria
0
  • argentina
  • chile
  • colombia
  • españa
  • méxico
  • perú
  • estados unidos
  • internacional

Select your country

Americas

Europe

Rest of the world

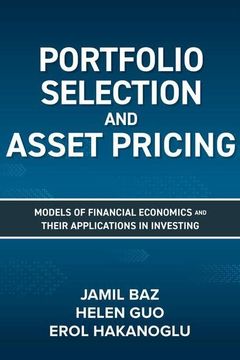
portada Portfolio Selection and Asset Pricing: Models of Financial Economics and Their Applications in Investing
Type
Physical Book
Language
English
Format
Hardcover
Dimensions
23.7x15.2x3.7 cm
Weight
0.66 kg.
ISBN13
9781264270156

Portfolio Selection and Asset Pricing: Models of Financial Economics and Their Applications in Investing

Jamil Baz (Author) · Helen Guo (Author) · Erol Hakanoglu (Author) · McGraw-Hill Companies · Hardcover

Portfolio Selection and Asset Pricing: Models of Financial Economics and Their Applications in Investing - Baz, Jamil ; Guo, Helen ; Hakanoglu, Erol

New Book Imported to Austria
Delivery: 27 Nov - 02 Dec Shipping: 9 to 11 business days.
80,60 €
Import costs and 10% VAT included in the price ✅
80,60 €

Synopsis "Portfolio Selection and Asset Pricing: Models of Financial Economics and Their Applications in Investing"

This uniquely comprehensive guide provides expert insights into everything from financial mathematics to the practical realities of asset allocation and pricingInvestors like you typically have a choice to make when seeking guidance for portfolio selection―either a book of practical, hands-on approaches to your craft or an academic tome of theories and mathematical formulas.From three top experts, Portfolio Selection and Asset Pricing strikes the right balance with an extensive discussion of mathematical foundations of portfolio choice and asset pricing models, and the practice of asset allocation. This thorough guide is conveniently organized into four sections: Mathematical Foundations―normed vector spaces, optimization in discrete and continuous time, utility theory, and uncertaintyPortfolio Models―single-period and continuous-time portfolio choice, analogies, asset allocation for a sovereign as an example, and liability-driven allocationAsset Pricing―capital asset pricing models, factor models, option pricing, and expected returnsRobust Asset Allocation―robust estimation of optimization inputs, such as the Black-Litterman Model and shrinkage, and robust optimizersWhether you are a sophisticated investor or advanced graduate student, this high-level title combines rigorous mathematical theory with an emphasis on practical implementation techniques.

Customers reviews

Frequently Asked Questions about the Book

All books in our catalog are Original.
The book is written in English.
The binding of this edition is Hardcover.

Questions and Answers about the Book

Do you have a question about the book? Login to be able to add your own question.

Opinions about Bookdelivery

More customer reviews